The premiums got too expensive
Costs rose and the policy no longer fits the budget. Find out what it is worth before the grace period runs out.
Before you let a policy lapse or hand it back to the insurance company, find out what it could sell for. Checking costs nothing and does not change your coverage.
Market averages reported by the Life Insurance Settlement Association. These are averages across thousands of different policies, not three outcomes for the same one. Your policy may be worth much more or much less.
Source: Life Insurance Settlement Association, 2025 Annual Market Data, 19 May 2026. Sellers received close to nine times the average cash surrender value.
The gap is widening because insurers are paying less: the average surrender offer fell 27% in 2025. Most policies do not qualify to be sold at all. The full comparison.
If any of these sound like your situation, your policy may be worth reviewing.
Costs rose and the policy no longer fits the budget. Find out what it is worth before the grace period runs out.
The children are grown, the mortgage is paid, the partner retired. The reason you bought it has gone.
This is a viatical settlement, not a life settlement. Different rules, and typically several times the payout.
A change in health can increase what buyers will pay, and may open a different route entirely.
Care costs arrive monthly. A policy can help fund them without touching your other assets.
When the arrangement behind a policy ends, there is often real value still sitting in it.
Four steps, usually 60 to 90 days from start to payment. You can stop at any point.
Two minutes on the form below, or a phone call if you would rather talk. We need the face amount, the type of policy and the insured's age and general health. No documents yet.
Most policies do not. If yours is one of them, we will say so on that first call rather than string you along. There is no cost either way.
We refer qualified policies to a licensed life settlement broker who represents you, not the buyers. They put your policy in front of multiple institutional purchasers so those buyers bid against each other.
The broker brings you the offers received. You can accept one, ask them to negotiate, or walk away and keep your policy exactly as it is. Nothing is owed unless a sale closes.
Which one applies to you depends mostly on health. A viatical settlement is the route for someone who is seriously ill, and it usually pays a much larger share of the death benefit.
Typical ranges only, drawn from published industry sources. Eligibility, pricing, tax treatment and timing vary by policy, insurer and state. Nothing here is a valuation of your policy or tax advice.
A terminal or chronic diagnosis means you are looking at a viatical settlement, not a life settlement. It is regulated separately, typically pays several times more, and the proceeds may qualify for exclusion from federal income tax where the requirements are met.
What to do after a diagnosis · How viatical settlements work
Almost nobody arrives knowing this, and it is the difference between a fair price and a poor one. There are four kinds of company involved and they want different things.
Licensed companies that purchase your policy with their own money and take over the premiums. Selling to one directly is fast, but there is a single offer on the table and their incentive is to pay as little as they reasonably can.
Licensed to represent you rather than the buyers. A broker takes your policy to several providers at once so they bid against one another, and is paid out of the proceeds. Why that changes the price.
We do not buy policies and we are not licensed to broker them. We explain the process, screen whether your policy is likely to qualify, and pass qualified files to a licensed broker. We are paid by that broker, only if a sale closes.
One buyer's offer tells you what that buyer is prepared to pay. It does not tell you what the policy is worth, because nothing has been tested against anyone else.
Policies that go to several buyers at once tend to end up somewhere different from where the first offer sat. Not always higher, but you have no way of knowing which case you are in until it happens.
Send us the offer before you sign anything. There is no cost, and if the number in front of you turns out to be a good one, we will tell you that too.
You have an offer in hand
Get a second look at itYou have not been made one
See what my policy is worthOur model is simple enough to state before you give us anything, so here it is in plain language.
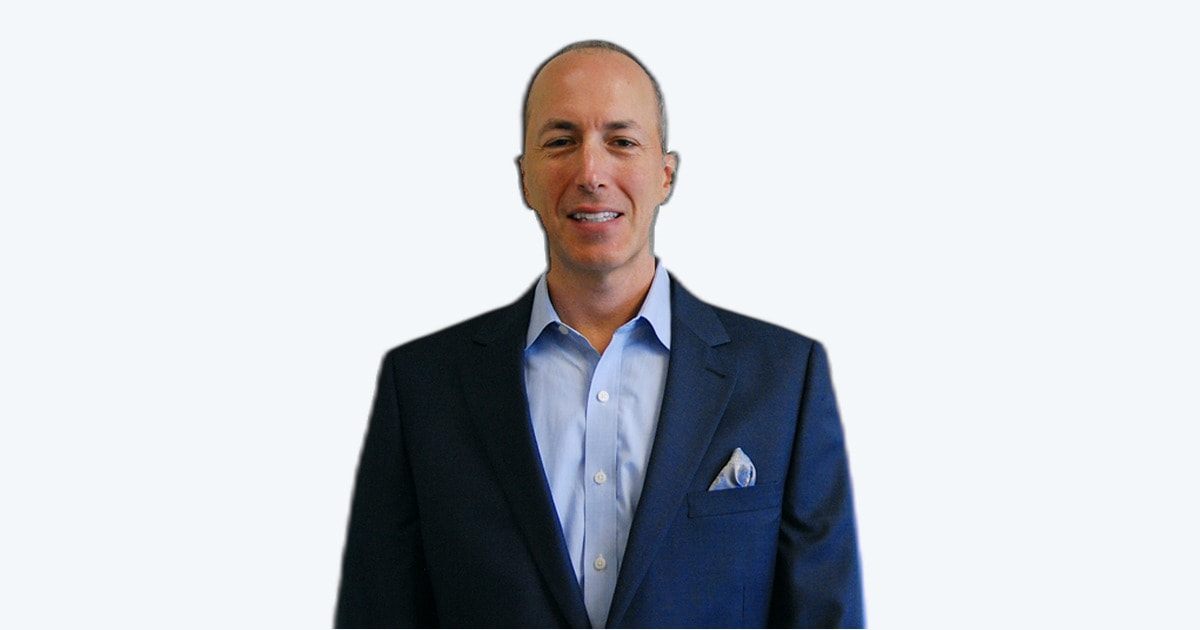
You are about to give a stranger your name, your phone number and something about your health. It is reasonable to want to know who is on the other end of that.
Larry Hoffman has spent over 20 years in legal funding and commercial lending, advancing capital against the future proceeds of legal claims. A life insurance policy poses the same question: what is a future payment worth today? Most people who own one have never been told it can be sold at all.
Tell him about the policy and he will give you a straight answer about where you stand, usually the same day. If it looks viable, a licensed broker takes it from there and runs the competitive process. Zen Cash is paid by that broker only if a sale closes.
Four short steps. No documents, no medical records, no credit check, and nothing changes about your coverage.
Step 1 of 4
Ready to find out?
The full form is on our contact page — four short questions, no documents needed.
See what my policy is worthor call (917) 576-0557
No. You can stop at any point, including after offers come in. You can decline the transaction and keep your policy, and you will owe nobody anything.
Yes, substantially. You are looking at a viatical settlement rather than a life settlement: age stops mattering, the payout is typically several times larger, and the proceeds may qualify for exclusion from federal income tax where the requirements are met. Some states set a minimum a buyer cannot go below. Before any of that, check whether your policy has an accelerated death benefit rider.
Nobody can tell you that until buyers have looked at the policy. Life settlements commonly land somewhere around 10 to 25 percent of the death benefit, though published ranges differ. Be careful of anyone who quotes you a figure before reviewing your file.
Usually 65 or older. If the insured person has a serious health condition, younger policies can qualify too. Policies under $100,000 rarely find a buyer.
Often yes, if it can be converted to a permanent policy first. Many term policies include that option and most people never realise it is there. Check before your conversion window closes.
Usually 60 to 90 days, though it varies. The slowest part is collecting medical records from doctors' offices, which is largely outside anyone's control.
It can. A lump sum may count as an asset and affect eligibility for needs-based programs. Raise this early so it can be planned around rather than discovered afterwards.
It goes to us and to the licensed broker handling your file, and to the buyers reviewing your policy under confidentiality. We do not sell it to marketing lists. You can ask us to delete your file at any time.
Nothing out of pocket at any stage. The broker's commission comes out of the settlement proceeds only if a sale closes. If you decide not to sell, you owe nobody anything.
All questions, including tax treatment and what happens if you change your mind →
Most do not. Checking costs nothing and does not change your coverage in the meantime.